Blog / Featured
Blog / company
AI in mortgage lending: Where does it fit?
Mortgage teams are turning to AI to improve their margins. Where does it help, and where do defined rules and calculations work better?
Large language models (LLMs) can produce different outputs from the same input. That variability presents a challenge for mortgage lending, where lenders need to explain their decisions and apply their policies consistently.
I recently attended the ACT Tech Summit, where four AI underwriting companies demonstrated their products and debated their approaches in front of lenders.
The question lenders kept asking was:
What happens if your AI makes a mistake?
It’s an understandable question. When all four companies evaluated the same loan application, completion times ranged from five minutes to more than an hour. One company’s AI denied the loan entirely.
What requirements do lenders need to meet?
Fannie Mae’s Lender Letter LL-2026-04 and Freddie Mac’s Guide Bulletin 2025-16 address AI governance for their sellers and servicers. Their requirements differ, but both call for documented policies, clear accountability, and risk management when using AI or machine learning.
Key requirements include:
- Document AI governance: Cover development, deployment, use, maintenance, and risk management, including oversight of vendors.
- Assign accountability: Designate policy owners, communicate responsibilities, and review policies at least annually. Freddie Mac’s AI requirements also explicitly require senior management approval.
- Be ready to explain AI use: Promptly disclose the systems used, their purposes, and the safeguards in place when the applicable agency requests that information.
Those requirements become more concrete when you look at an underwriting workflow.
Breaking down AI underwriting
Your borrower completes the Uniform Residential Loan Application, commonly called the 1003, and uploads a recent paystub, W-2s, and supporting documents. You use an AI underwriting system to automate part of the review.
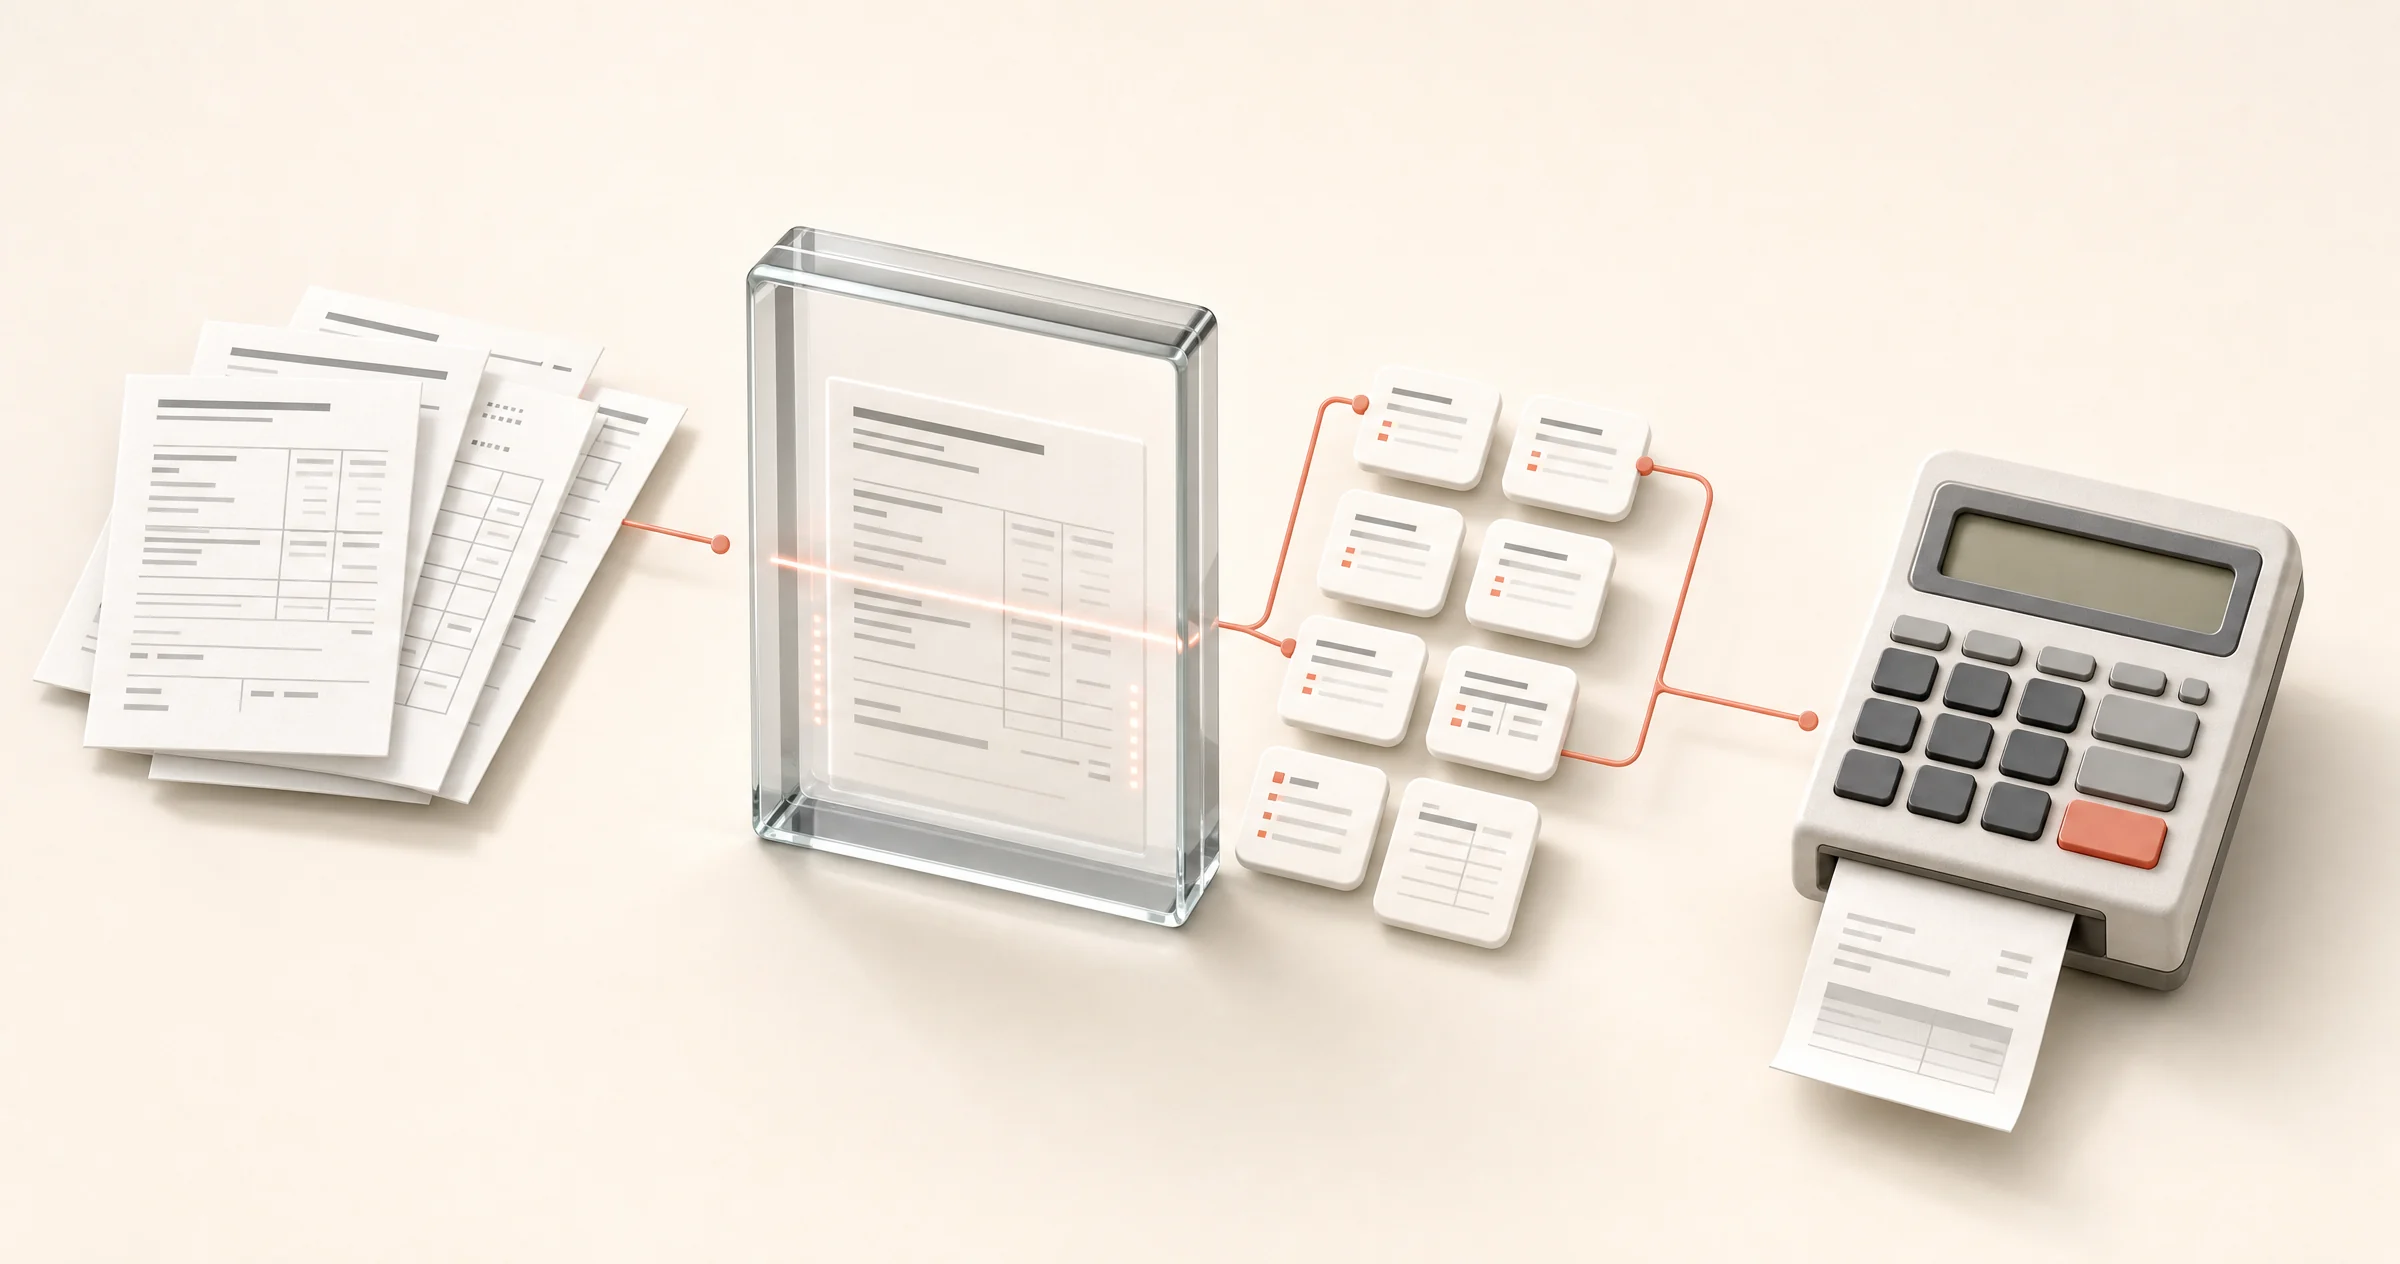
For income qualification, the workflow breaks down into four steps:
- Classify the documents: Identify each upload as a paystub, W-2, or another document type.
- Extract the data: Read the pay rate, year-to-date gross earnings, and other relevant fields.
- Calculate qualifying income: Apply the appropriate income calculation to the verified data.
- Check the product’s requirements: Use qualifying income and the borrower’s debts to calculate the debt-to-income ratio and assess it against the applicable guidelines.
An LLM can assist with this workflow, but its output alone doesn’t establish that each step was correct. Underwriting involves judgment as well as rules, and lenders remain responsible for fair, consistent decisions supported by evidence.
What happens if the AI makes a mistake?
At the summit, the companies’ answers varied, but they centered on two approaches:
- A warranty or guarantee: Financial protection intended to cover specified losses if an AI error leads to a loan repurchase.
- Human review: An underwriter reviews and signs off on the AI’s work before closing.
Both approaches address responsibility for the result. Neither, on its own, explains how the system arrived at that result.
For income qualification, a meaningful sign-off needs to establish that:
- The document classifications are correct.
- The data used in the calculation match the source documents.
- The income calculation follows the applicable guidelines.
- The resulting debt-to-income ratio meets the product’s requirements.
The first two steps involve interpreting documents. Once the data and applicable rules are established, the last two can use repeatable calculations and explicit eligibility checks. They don’t all need the same tool.
A more deterministic approach
Sending loan documents and guidelines to an LLM and asking it to handle the entire process makes the result harder to validate. It also asks the model to do work that conventional software can perform consistently.
Break the process into steps and use AI where it helps. Paystubs can look drastically different from one employer to another, making document classification and data extraction useful applications for AI. Keep the source references and flag unclear or conflicting information for review.
Income calculation can then follow defined rules. For a salaried borrower, inputs used to calculate and validate base income include:
- Pay rate
- Pay frequency
- Year-to-date gross earnings
- Pay period end date
- Loan product and applicable guideline version
These inputs don’t establish eligibility on their own. Employment history, income stability, and other product requirements still matter. But once you’ve verified the inputs and established the applicable rules, the calculation should produce the same result every time.
You don’t need an LLM to perform that calculation.
A process you can explain and audit
This approach lets you apply a documented income qualification policy across your organization. When someone asks why you used a particular qualifying income, you can show the source documents, verified inputs, rules, and calculation that produced it.
An LLM can use that same calculator. It can supply the required inputs and retrieve the result without having to work out the formula each time. Your team and your AI tools use the same calculation logic.
Repeatability alone doesn’t guarantee correctness: the data and rules still need validation. But separating document interpretation from calculation makes errors easier to locate, explain, and correct. It can also reduce avoidable calculation errors that contribute to repurchase risk.
That’s where AI fits: interpreting documents while defined rules and calculations make the result reproducible and auditable.
To see how this approach works in practice at Gizmo, reach out to us.